
Most advice about a roof home warranty starts in the wrong place. Homeowners ask whether the plan covers a roof leak, but the harder question is why the leak happened, whether the roof was eligible when coverage began, and which party is responsible for the repair. A warranty isn't a substitute for homeowners insurance, a manufacturer warranty, or a qualified roofing inspection.
That distinction matters across California, where aging roofs, storm damage, maintenance problems, installation defects, and permit requirements frequently overlap. A contract may promise roof protection, yet still deny a claim because the damage existed before enrollment, the roof is too old, the affected area exceeds the repair scope, or the failure traces back to workmanship. The practical goal is simple: classify the problem correctly before filing, then choose the fastest path to a watertight and code-compliant roof.
Table of Contents
- What a Roof Home Warranty Covers
- Roof Home Warranty vs Manufacturer Roofing Warranties
- Classifying Your Roof Problem Before Filing a Claim
- Common Exclusions That Kill Roof Warranty Claims
- Navigating the Roof Warranty Claim Process
- When a Professional Roof Inspection Is the Better Path
- Protecting Your Roof Investment in California
What a Roof Home Warranty Covers
A roof home warranty is a limited repair contract, not a promise to replace a failing roof. Its value depends on whether the problem is localized, nonstructural, and inside the plan's stated limits. Most plans pay for small repairs, not full replacement, and many cap roof-related payouts at a modest amount that leaves the homeowner covering the rest.
Covered work usually involves a damaged shingle, a flashing failure, a small puncture, a popped-up nail, a seam issue, or a limited underlayment or membrane repair. These are isolated defects a technician can identify and fix without tearing apart the whole roof system. The contract may restore water-tightness at the leak point, but it usually will not pay for broad tear-off work, structural repair, or a full replacement just because the roof is old.
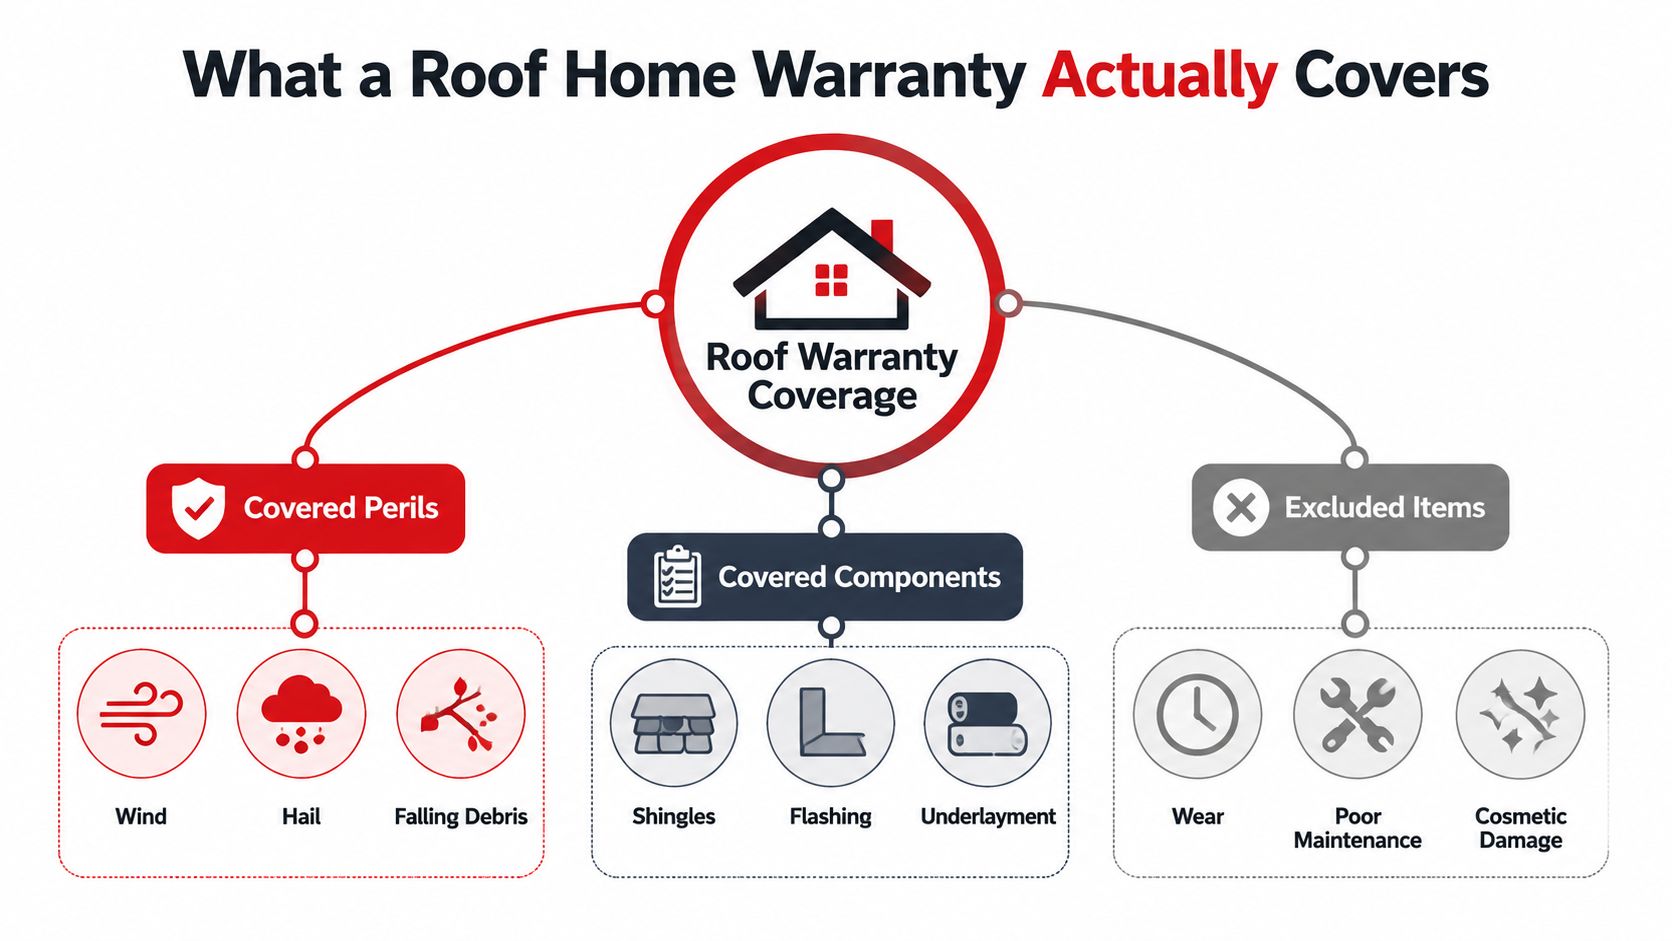
The repair boundary matters
A leak over an occupied room can still qualify if the inspection ties it to a covered defect. Widespread deterioration, structural movement, storm-created damage, or a roof that needs replacement usually falls outside that narrow lane. The visible symptom may look the same, but the cause controls the claim.
Homeowners also need to separate a consumer service contract from roofing guidance. Resources like the Swannee2 roofing guide can help readers build vocabulary, but they cannot override the exclusions or payout limits written into a warranty contract.
Practical rule: A roof home warranty is a repair-level safety net. It is not replacement insurance.
Before buying coverage, ask for the full contract, identify the roof-specific cap, check how the plan defines a covered leak, and confirm whether the roof's age and material are eligible. A low-cost plan can still leave a large balance if the actual fix requires extensive labor, decking replacement, code upgrades, or a new roof system.
Roof Home Warranty vs Manufacturer Roofing Warranties
The word warranty covers several different agreements, and homeowners get burned when they file the claim with the wrong party. A home warranty is a limited service contract for certain repairs. A manufacturer warranty deals with defects in roofing products. A workmanship warranty deals with installation errors by the roofing contractor. Those are different claims, different rules, and different documents.
Three warranty types sit side by side, and each answers a different question: who fixed it, what failed, and whether the roof meets the contract terms. Manufacturer warranties commonly run 10 to 30 years, with some products reaching 50 years or lifetime terms depending on the product and installer, according to a guide comparing roof warranty duration and coverage terms. Length alone means nothing if the roof was installed outside the spec, poorly maintained, or damaged by something the policy excludes.
Roof coverage types compared
| Criteria | Home Warranty | Manufacturer Warranty | Workmanship Warranty |
|---|---|---|---|
| Main purpose | Limited repair for covered roof problems | Protection against specified material or manufacturing defects | Correction of installer-caused errors |
| Typical trigger | A qualifying repair-level leak or failure under the service contract | A product fails to perform according to the manufacturer's terms | Flashing, fastening, detailing, or installation work was defective |
| Administrator | Home warranty provider or assigned service contractor | Roofing material manufacturer, sometimes through an approved installer | Original roofing contractor |
| Replacement scope | Usually limited and subject to contract caps and exclusions | Depends on the product terms and confirmed defect | Depends on the contractor's written promise and responsibility |
| Best evidence | Contract, ownership records, installation information, and damage photos | Product details, installation records, and proof of compliant assembly | Contract, invoices, photographs, and an inspection tying the failure to workmanship |
A manufacturer claim makes sense when a membrane, shingle, coating, or flashing product fails even though it was installed correctly. A workmanship claim fits when the installer used the wrong fasteners, misapplied sealant, or failed to integrate flashing the way the roof system required. A home warranty may cover a smaller repair if the contract allows it, but it does not erase the limits of the other two warranties.
California homeowners looking at claim boundaries should also read this guide to roof replacement coverage under homeowners insurance. The core issue is cause. Put the claim in front of the party responsible for the failure, and you avoid wasted time, denied paperwork, and the usual blame shuffle.
Classifying Your Roof Problem Before Filing a Claim
The most useful question isn’t “Do warranties cover leaks?” It’s “What caused this leak?” A roof inspection should separate four categories: sudden peril, installation defect, maintenance failure, and aging materials. Each category points toward a different payer or remedy.
A wind event, hail impact, fire, or certain water-related losses generally belong with homeowners insurance, while aging materials, poor maintenance, and normal wear are usually excluded from that type of policy, as explained in this overview of roofs and home insurance. A workmanship warranty is more appropriate when the roof failed because the installer performed defective work. A home warranty may be relevant only when the contract accepts the specific repair and the roof meets its eligibility conditions.
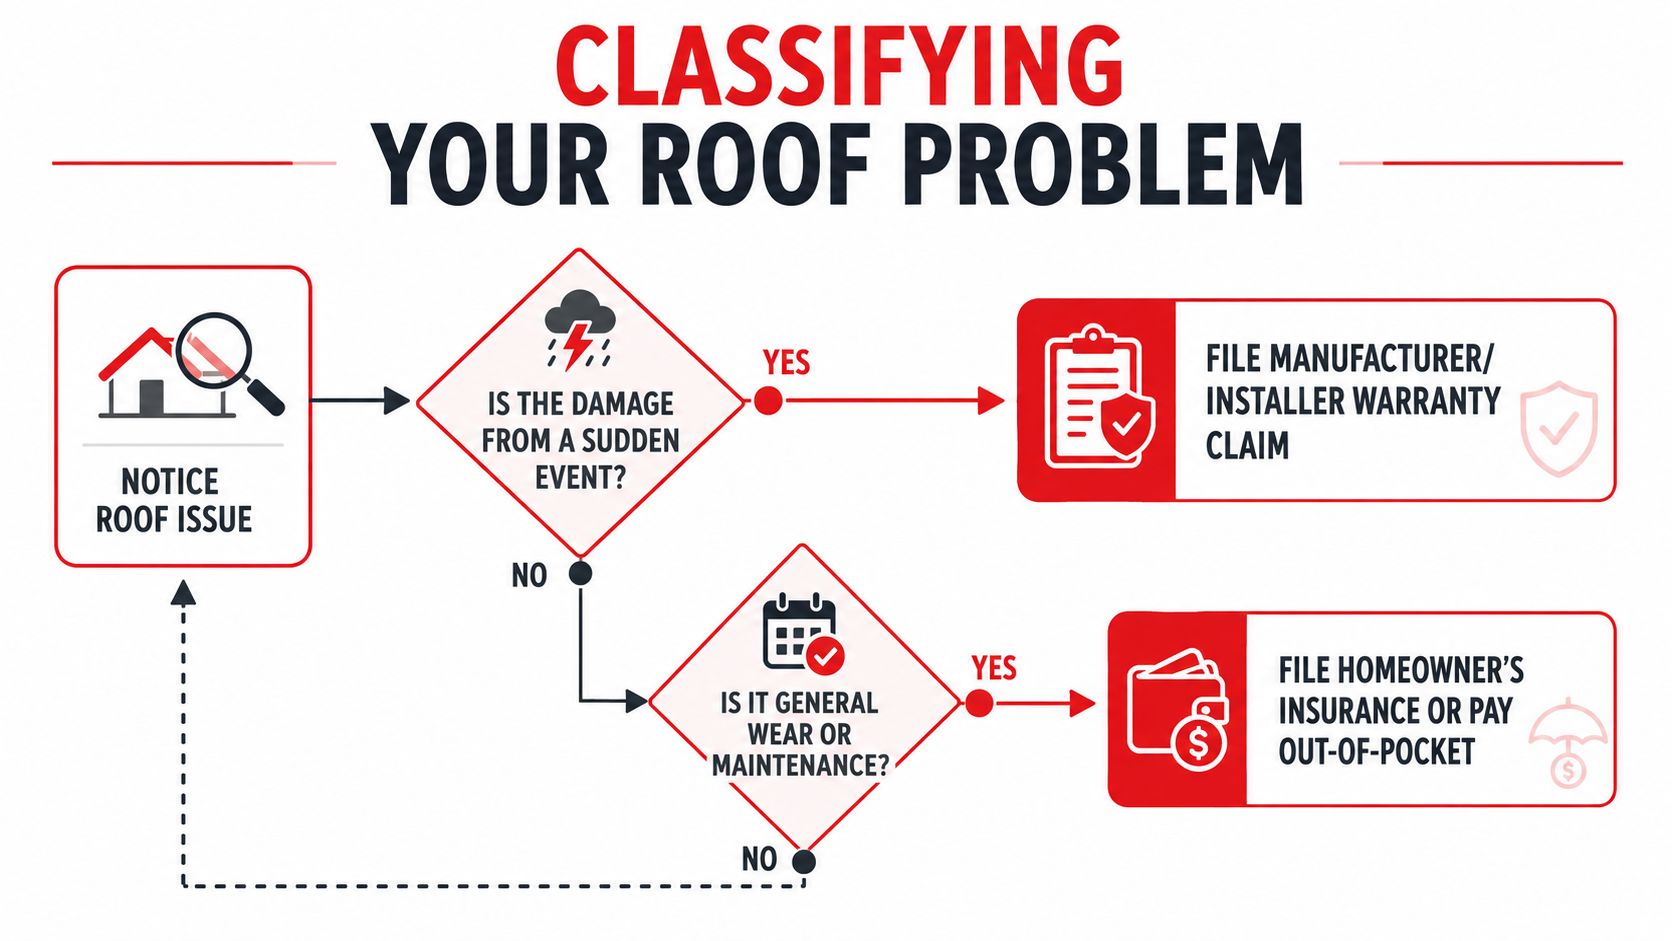
Four causes, four different paths
- Sudden event: Look for displaced materials, impact marks, punctures from falling debris, or a defined weather date. The homeowner should document the condition and contact the insurance carrier before authorizing broad repairs.
- Installation defect: Look for recurring leaks at valleys, penetrations, wall transitions, flashing, or fastener lines. The installer or manufacturer may need to inspect the assembly and review installation records.
- Maintenance issue: Blocked drainage, neglected sealant, damaged components, and deferred repairs generally point to homeowner-funded maintenance rather than warranty protection.
- Aging system: Widespread brittleness, granule loss, membrane deterioration, recurring leaks, or exposed substrate can indicate that repair is no longer the sensible remedy.
A homeowner who files a warranty claim for storm damage may receive a denial because the service contract excludes weather events. Someone who files insurance for slow deterioration may face the opposite result. The same interior stain can therefore produce completely different outcomes depending on its origin.
For a neutral starting point, a local contractor can document the failure before the claim is submitted. California homeowners can review roof repair services and inspection support when the cause remains unclear or the leak has already spread beyond a simple patch.
Common Exclusions That Kill Roof Warranty Claims
Many claims fail before anyone discusses the repair method. The provider first asks whether the roof was eligible, whether the condition existed before coverage began, and whether the affected material falls inside the contract definition. Homeowners who skip those checks often pay for a service visit only to learn that the contract never applied.
Common exclusions include preexisting damage, roofs beyond a specified age, certain roof types such as metal or green roofs, solar panels, chimneys, and full roof replacement, according to this summary of roof home warranty exclusions. Contracts may also restrict inaccessible areas, renovation-related damage, recalled materials, and work that exceeds the stated payout limit.
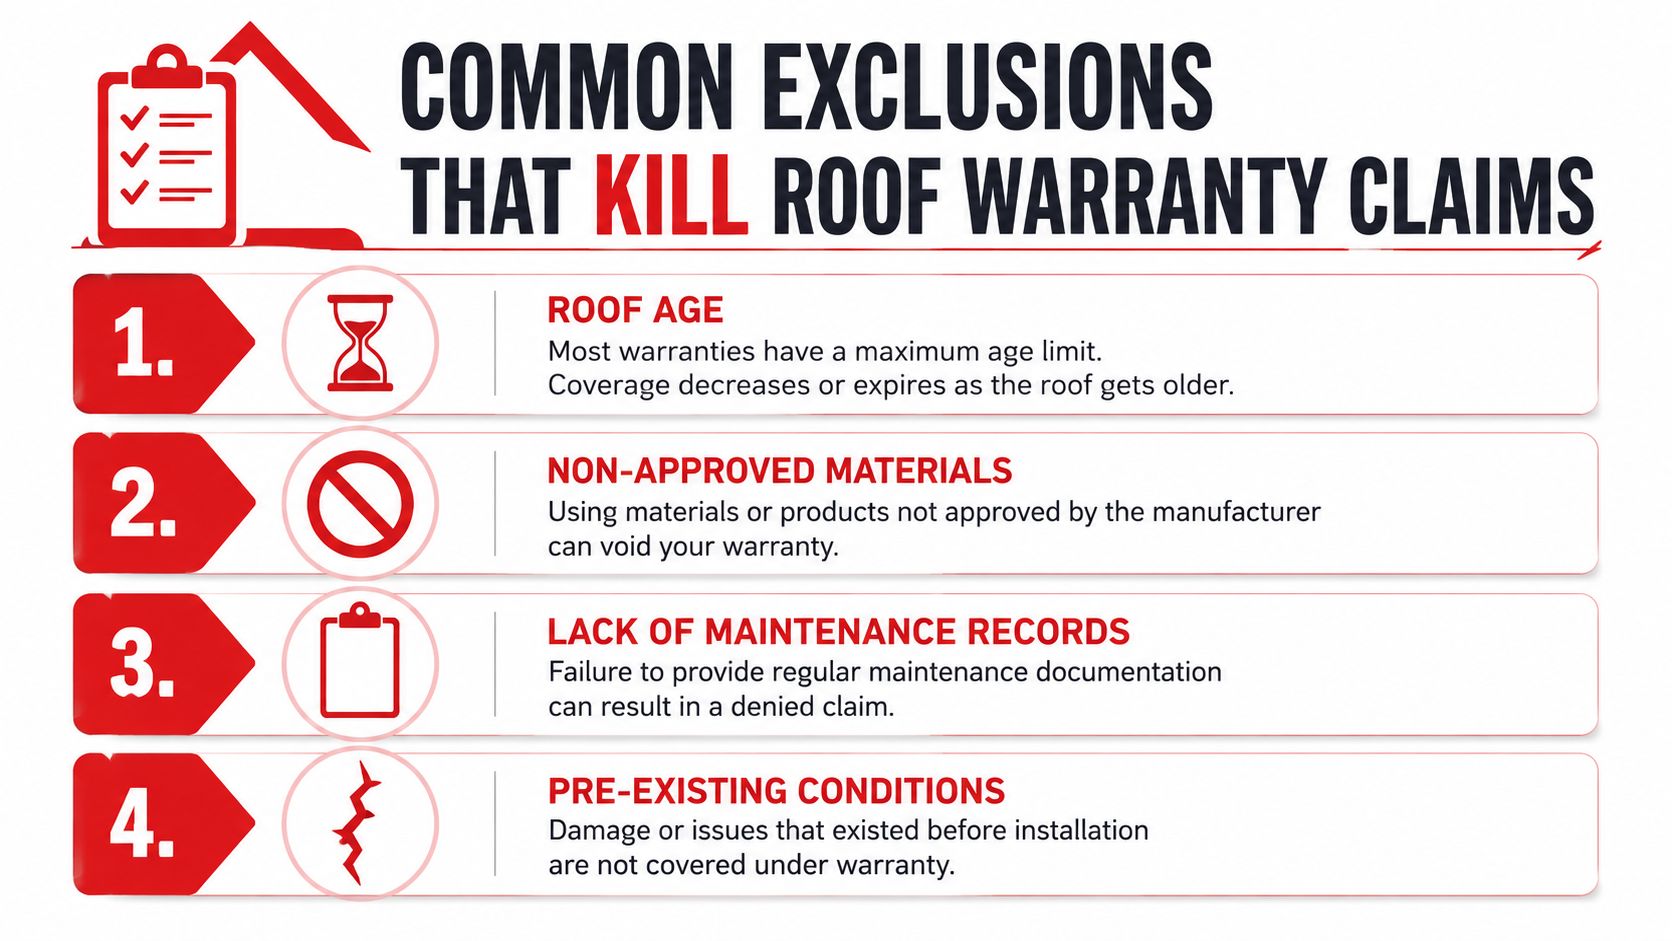
Check eligibility before paying for coverage
Start with the roof’s history. Find the installation invoice, prior inspection reports, repair receipts, insurance records, and photographs. A slow leak, loose shingle, or known defect that predates the contract can make the condition preexisting.
Confirm the material and accessories. A plan may treat a conventional shingle roof differently from a metal or vegetated assembly. Solar equipment, chimneys, and rooftop additions may be excluded or assigned to another party, even when the surrounding roof is eligible.
Review maintenance obligations. Contracts commonly expect reasonable upkeep. Blocked drainage, neglected penetrations, failed sealants, and unrepaired damage give a provider an argument that the homeowner allowed the condition to worsen.
Look for scope traps. A contract might cover the leak source but not interior damage, structural decking, code upgrades, access work, or replacement of the entire system. The repair can therefore be technically covered while the necessary project remains financially impractical.
A policy that covers “roof leaks” can still exclude the roof condition that caused the leak.
For older California homes, a pre-purchase inspection and written eligibility confirmation are more useful than a broad sales description. The contract language should answer whether the roof qualifies before the homeowner relies on it.
Navigating the Roof Warranty Claim Process
A strong claim is built from records, not from a description of a ceiling stain. Providers commonly need proof of ownership, the installation date, the contract itself, and photographs showing where water entered and what changed. Recent coverage examples also demonstrate that documentation can determine whether the claim advances at all.
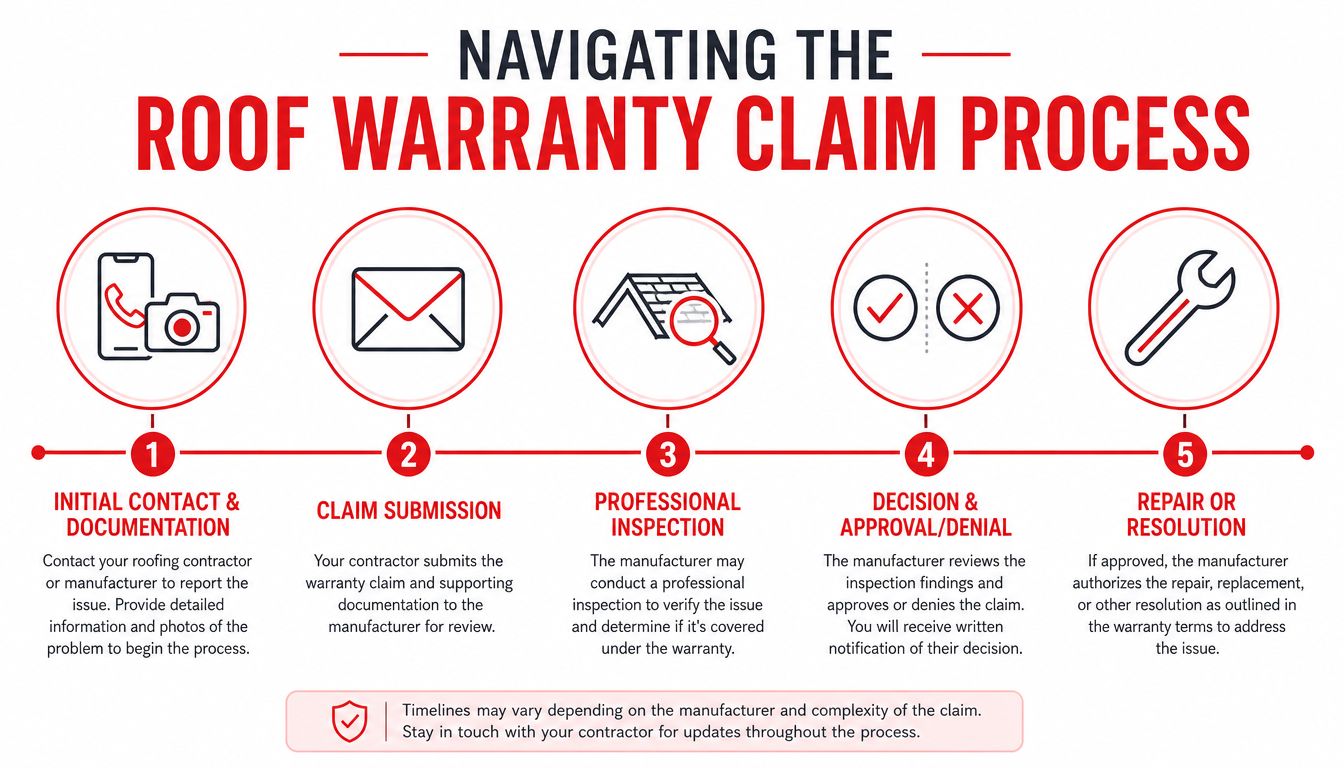
Build the file before opening the claim
- Record the condition. Photograph the interior stain, attic evidence, roof surface, flashing, drainage paths, and any visible debris or displacement. Keep the original images and note when the problem was first observed.
- Gather ownership and installation proof. Collect the purchase documents, roof invoice, permit information if available, maintenance records, and prior repair paperwork.
- Read the claim procedure. Use the required phone number, portal, or form. Ask whether the provider must authorize inspection or repairs before a contractor begins work.
- Describe facts, not conclusions. “Water appeared below the upstairs valley after rainfall” is more useful than declaring that a particular warranty must pay. The inspection should establish the cause.
- Request the decision in writing. If the claim is denied, the written explanation should identify the exclusion, eligibility failure, or scope limit used.
The assigned inspector should distinguish a roof defect from attic condensation, plumbing leakage, drainage overflow, and storm impact. If the first assessment doesn’t explain the evidence, the homeowner can request a second inspection or obtain an independent report before accepting the decision.
Claims often stall when the homeowner authorizes emergency work that changes the evidence, lacks installation records, or waits while water continues entering the building. Temporary measures may protect the property, but permanent work should follow the contract’s authorization rules whenever conditions allow.
When a Professional Roof Inspection Is the Better Path
A warranty claim only makes sense when the contract clearly matches the problem. Direct roofing help is the better move when the roof is past repair, the likely fix cost runs into the policy limit, the system is outside coverage, or waiting will keep damaging insulation, decking, framing, or interior finishes.
A solid inspection has to do more than look for a stain. It should identify the leak source, check flashings and penetrations, inspect the attic where access allows, review the substrate and any structural concerns, document roof age and materials, and separate storm damage from wear and deterioration. Commercial properties may also need moisture mapping. For infrared work, ASTM C1153 is the recognized standard practice for locating wet insulation in roofing systems, and a a guide to commercial roof inspection standards explains how that kind of documentation supports a defensible finding.
California project limits change the decision
California permit rules can turn a small-looking repair into a regulated reroofing job. In one California jurisdiction, repairs under 10% of the roof area or 200 square feet, whichever is less, may proceed without a permit, while work above that threshold requires a reroof permit and code compliance, as stated in this California residential roof recovering guideline.pdf).
Other local rules can require a permit when sheathing is replaced, when dry rot repairs reach 32 square feet or more of replaced decking, or when structural members are altered, according to this California residential reroof information handout. Commercial reroofing may require removing existing roof assembly layers down to the deck under the applicable code provisions, as described in this California non-residential reroof handout.
A qualified contractor should give written findings, photographs, a defined repair or replacement scope, permit guidance, and warranty terms. Property owners comparing inspection resources can also review this Marietta tree removal cost for general budgeting context, although roofing scope still calls for a roofing-specific assessment. California owners should use professional roof inspections when the claim turns on cause, extent, or code requirements.
Protecting Your Roof Investment in California
A roof stays protected when each layer of responsibility is documented. Homeowners insurance is generally the route for covered sudden events. A manufacturer warranty addresses qualifying product defects. A workmanship warranty addresses installer errors. A roof home warranty may help with a narrowly defined repair, but it shouldn’t be treated as the primary plan for an aging or failing roof.
The strongest protection starts before the leak. Owners should retain installation records, photograph completed flashing and penetrations, schedule documented inspections, clear drainage paths, and address minor defects before water reaches the deck. Commercial owners should preserve inspection reports and moisture survey findings, especially when a warranty depends on an approved roof assembly.
Installation specification also matters. Commercial membrane system warranties can require approved membrane thickness, cover boards, fasteners, fastening patterns, adhesive coverage, and other assembly details before long-term coverage applies. A premium material doesn’t protect the claim if the installer deviates from the approved system.
For California properties, the practical recommendation is direct: inspect first, classify the cause, read the exclusions, and confirm permit requirements before filing or repairing. A licensed contractor can then coordinate warranty documentation, insurance evidence, repair planning, or full replacement without forcing every roof problem through the wrong channel.
California Roof Pros provides roof inspections, leak repairs, replacements, commercial roofing, written findings, and insurance claim assistance for properties across Concord and the East Bay. Property owners can visit California Roof Pros to request an assessment, clarify warranty gaps, and get a defined path toward repair or replacement.

The CA Roof Pros Editorial Team brings together roofing professionals and experienced content specialists dedicated to providing accurate, practical information about roofing, repairs, maintenance, and replacement. Every article is researched and reviewed to help California homeowners make informed decisions about their roofing needs.